HR10690Referred to Committee
Capital Loss Inflation Fairness Act
Introduced
In Committee
3
Passed One Chamber4
Passed Both5
Signed into Law119th
Congress
2026-10-01
Introduced
7
Cosponsors
HR
ⓘType
Sponsor
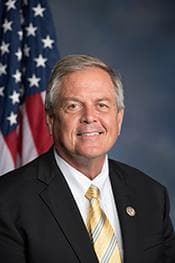
Ralph Norman
Republican · SC · Representative
Votes with party: 86.1% (597 recorded votes)
Full profile: /officials/N000190
Source: Congress.gov · FEC
Cosponsors (7)
Members who have signed on to support this bill since introduction. Source: Congress.gov.
Latest Action
The most recent step in the bill's legislative path. Committee Activity below shows referrals and reports; the full action-by-action history including floor proceedings lives at Congress.gov →
Committee Activity
Currently in
- House Committee on Ways and MeansReferred To · 2026-10-01
Plain-English Summary
Plain-English summary pending. Introduced on 2026-10-01. Check back soon — summaries are generated as bills progress through Congress.
Full Bill Text
Verbatim text published on Congress.gov via GovInfo. Use Cmd+F / Ctrl+F to search within this excerpt.
[Congressional Bills 119th Congress] [From the U.S. Government Publishing Office] [H.R. 10690 Introduced in House (IH)] <DOC> 119th CONGRESS 2d Session H. R. 10690 To amend the Internal Revenue Code of 1986 to increase the limitation on capital losses and index the limitation to inflation. _______________________________________________________________________ IN THE HOUSE OF REPRESENTATIVES October 1, 2026 Mr. Norman (for himself, Mrs. Biggs of South Carolina, Mr. Harris of Maryland, Mr. Cloud, and Mr. Massie) introduced the following bill; which was referred to the Committee on Ways and Means _______________________________________________________________________ A BILL To amend the Internal Revenue Code of 1986 to increase the limitation on capital losses and index the limitation to inflation. Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled, SECTION 1. SHORT TITLE. This Act may be cited as the ``Capital Loss Inflation Fairness Act''. SEC. 2. INCREASED LIMITATION ON CAPITAL LOSSES. (a) In General.--Section 1211(b) of the Internal Revenue Code of 1986 is amended to read as follows: ``(b) Other Taxpayers.-- ``(1) In general.--In the case of a taxpayer other than a corporation, losses from sales or exchanges of capital assets shall be allowed only to the extent of the gains from such sales or exchanges, plus (if such losses exceed such gains) the lower of-- ``(A) $14,250 ($7,125 in the case of a married individual filing a separate return), or ``(B) the excess of such losses over such gains. ``(2) Inflation adjustment.--In the case of any taxable year beginning in a calendar year after 2026, the dollar amounts in paragraph (1)(A) shall be increased by an amount equal to-- ``(A) such dollar amount, multiplied by ``(B) the cost-of-living adjustment under section 1(f)(3) for the calendar year in which the taxable year begins, determined by substituting `calendar year 2025' for `calendar year 2016' in subparagraph (A)(ii) thereof. If any increase determined under the preceding sentence is not a multiple of $25, such increase shall be rounded to the nearest multiple of $25.''. (b) Effective Date.--The amendment made by this section shall apply to losses in taxable years beginning after December 31, 2025. <all>
Related legislation
Bills by the same sponsor or covering overlapping subjects.
- HR9361Worst of the Worst ActReferred to Committee · 2026-06-18
- HR4463To amend the Catawba Indian Tribe of South Carolina Land Claims Settlement Act of 1993.Passed House · 2026-06-03
- HR9103Merit Restoration ActReferred to Committee · 2026-06-02
- HR3377To authorize the President to award the Medal of Honor to James Capers, Jr., for acts of valor as a member of the Marine Corps during the Vietnam War.Enacted into Law · 2026-03-26