HR10709Referred to Committee
Multigenerational HOMES Act
Introduced
In Committee
3
Passed One Chamber4
Passed Both5
Signed into Law119th
Congress
2026-10-01
Introduced
1
Cosponsors
HR
ⓘType
Sponsor
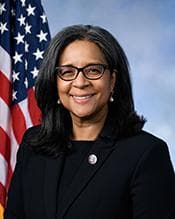
Marilyn Strickland
Democrat · WA · Representative
Votes with party: 97.9% (657 recorded votes)
Full profile: /officials/S001159
Source: Congress.gov · FEC
Cosponsors (1)
Members who have signed on to support this bill since introduction. Source: Congress.gov.
Latest Action
The most recent step in the bill's legislative path. Committee Activity below shows referrals and reports; the full action-by-action history including floor proceedings lives at Congress.gov →
Committee Activity
Currently in
- House Committee on Ways and MeansReferred To · 2026-10-01
Plain-English Summary
Plain-English summary pending. Introduced on 2026-10-01. Check back soon — summaries are generated as bills progress through Congress.
Full Bill Text
Verbatim text published on Congress.gov via GovInfo. Use Cmd+F / Ctrl+F to search within this excerpt.
[Congressional Bills 119th Congress] [From the U.S. Government Publishing Office] [H.R. 10709 Introduced in House (IH)] <DOC> 119th CONGRESS 2d Session H. R. 10709 To amend the Internal Revenue Code of 1986 to establish a tax credit for multigenerational home renovation expenditures. _______________________________________________________________________ IN THE HOUSE OF REPRESENTATIVES October 1, 2026 Ms. Strickland (for herself and Mr. Joyce of Ohio) introduced the following bill; which was referred to the Committee on Ways and Means _______________________________________________________________________ A BILL To amend the Internal Revenue Code of 1986 to establish a tax credit for multigenerational home renovation expenditures. Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled, SECTION 1. SHORT TITLE. This Act may be cited as the ``Multigenerational Housing Opportunities to Modify Existing Structures Act'' or the ``Multigenerational HOMES Act''. SEC. 2. NONREFUNDABLE PERSONAL CREDIT FOR MULTIGENERATIONAL HOME RENOVATION EXPENDITURES. (a) In General.--Subpart A of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after section 25F the following new section: ``SEC. 25G. MULTIGENERATIONAL HOME RENOVATION EXPENDITURES. ``(a) Allowance of Credit.-- ``(1) In general.--In the case of an individual, there shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to 15 percent of the qualified multigenerational home renovation expenditures made by the taxpayer during such taxable year. ``(2) Lifetime limitation per qualified dwelling unit of taxpayer.--Subject to subsection (b), the credit allowed under paragraph (1) with respect to any qualified dwelling unit of the taxpayer for any taxable year shall not exceed the excess (if any) of $7,500 over the aggregate credits allowed to such taxpayer (or, in the case of a married individual, such individual's spouse) under such paragraph with respect to such qualified dwelling unit for all prior taxable years. ``(b) Income Phaseout.-- ``(1) In general.--The amount of the credit allowed by subsection (a) (determined without regard to this subsection) shall be reduced (but not below zero) by the amount which bears the same ratio to such credit (as so determined) as--- ``(A) the excess of-- ``(i) the taxpayer's modified adjusted gross income for such taxable year, over ``(ii) $200,000 (twice such amount in the case of a joint return), bears to ``(B) $75,000. ``(2) Modified adjusted gross income.--For purposes of this subsection, the term `modified adjusted gross income' means adjusted gross income increased by any amount excluded from gross income under section 911, 931, or 933. ``(c) Refundable Credit for Certain Lower-Income Taxpayers.--In the case of any taxpayer whose adjusted gross income does not exceed the area median gross income (determined under rules similar to the rules of section 142(d)(2)(B)), the credit allowed under this section (determined without regard to this subsection) shall be treated as a credit allowed under subpart C (and not as a credit allowed under this section). ``(d) Definitions.--For purposes of this section-- ``(1) Qualified multigenerational housing expenditure.--The term `qualified multigenerational housing expenditure' means, with respect to any taxpayer, any expenditure for-- ``(A) tangible personal property which is directly related to-- ``(i) improving the safety, mobility, or accessibility of a qualified dwelling unit of the taxpayer for purposes of supporting any qualified relative of such taxpayer, or ``(ii) providing living quarters for any individual if the taxpayer is a qualified relative with respect to such individual and such individual provides care for such taxpayer, ``(B) labor properly allocable to the onsite preparation, assembly, or original installation of such property, and ``(C) inspections of such dwelling unit required under State or local law by reason…
Show the remaining 781 wordsHide the remaining 781 words
of the installation of such property. ``(2) Qualified dwelling unit.--The term `qualified dwelling unit' means a dwelling unit which-- ``(A) is located in the United States or in a territory of the United States, and ``(B) is either-- ``(i) used as a principal residence by the taxpayer, or ``(ii) a secondary unit located on the same property as such principal residence. ``(3) Qualified relative.-- ``(A) In general.--The term `qualified relative' means, with respect to any taxpayer for any taxable year, an individual-- ``(i) who bears a relationship described in subparagraph (B) to such taxpayer or to such taxpayer's spouse, ``(ii) who has attained age 65 as of the last day of such taxable year or is disabled (within the meaning of section 72(m)(7)), ``(iii) whose principal place of abode for more than one-half of such taxable year is a qualified dwelling unit of such taxpayer, and ``(iv) whose TIN is included on the taxpayer's return of tax for such taxable year. ``(B) Relationship.--For purposes of subparagraph (A), a relationship described in this subparagraph is a relationship described in subparagraph (B), (C), (D), (F), or (G) of section 152(d)(2), except that only a father-in-law, mother-in-law, brother-in-law, or sister-in-law shall be taken into account for purposes of subparagraph (G) thereof. ``(4) Principal residence.--The term `principal residence' has the same meaning as when used in section 121. ``(5) Safe harbor for delayed occupancy.--An expenditure shall not be treated as failing to satisfy the requirements of paragraph (1)(A) solely because the dwelling unit is not occupied by any person if such person occupies the dwelling unit not later than the date that is 1 year after the completion of the improvements referred to in such paragraph. ``(e) Inflation Adjustments.-- ``(1) In general.--In the case of any taxable year beginning after December 31, 2027, the $7,500 amount in subsection (a)(2), the $200,000 amount in subsection (b)(1)(A)(ii), and the $75,000 amount in subsection (b)(1)(B) shall each be increased by an amount equal to-- ``(A) such dollar amount, multiplied by ``(B) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, determined by substituting `calendar year 2026' for `calendar year 2016' in subparagraph (A)(ii) thereof. ``(2) Rounding.--If any increase determined under paragraph (1) is not a multiple of $50, such amount shall be rounded to the nearest multiple of $50. ``(f) Carryforward of Unused Credit.-- ``(1) In general.--If the credit allowable under subsection (a)(1) for any taxable year exceeds the applicable tax limit for such taxable year, such excess shall be a carryover to each of the 5 succeeding taxable years and, subject to the limitations of paragraph (2), shall be added to the credit allowable by subsection (a)(1) for such succeeding taxable year. ``(2) Limitation.--The amount of the unused credit which may be taken into account under paragraph (1) for any taxable year shall not exceed the amount (if any) by which the applicable tax limit for such taxable year exceeds the sum of-- ``(A) the credit allowable under subsection (a)(1) for such taxable year determined without regard to this subsection, and ``(B) the amounts which, by reason of this subsection, are carried to such taxable year and are attributable to taxable years before the unused credit year. ``(3) Applicable tax limit.--For purposes of this subsection, the term `applicable tax limit' means the limitation imposed by section 26(a) for the taxable year reduced by the sum of the credits allowable under this subpart (other than this section and section 25D). ``(g) Substantiation Requirement.--No credit shall be allowed under this section with respect to any multigenerational home renovation expenditure unless the taxpayer provides the Secretary with such documentation as the Secretary may require to substantiate such expenditure.''. (b) Conforming Amendments.-- (1) Section 23(c)(1) of such Code is amended by striking ``section 25D'' and inserting ``sections 25D and 25G''. (2) Section 25(e)(1)(C) of such Code is amended by striking ``and 25F'' and inserting ``25F, and 25G''. (3) Section 25F(f)(1) of such Code is amended by striking ``this section, section 23, and section 25D'' and inserting ``this section and sections 23, 25D, and 25G''. (4) Section 6211(b)(4)(A) of such Code is amended by inserting ``25G by reason of subsection (c) thereof,'' before ``32,''. (5) Section 1324(b)(2) of title 31, United States Code, is amended by inserting ``25G,'' after ``25A,''. (6) The table of sections for subpart A of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 25F the following new item: ``Sec. 25G. Multigenerational home renovation expenditures.''. (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2026. <all>
Related legislation
Bills by the same sponsor or covering overlapping subjects.
- HR10710Military Officer Promotion Integrity Act of 2026Referred to Committee · 2026-10-01
- HR8590CARE for Parenting Students ActReferred to Committee · 2026-04-29
- HR7515To direct the Secretary of the Interior to convey to the Nisqually Indian Tribe the Clear Creek Hatchery infrastructure.Referred to Committee · 2026-04-29
- HR83576PPD Task Force ActReferred to Committee · 2026-04-16