HR10944Referred to Committee
Homeownership Opportunity Act
Introduced
In Committee
3
Passed One Chamber4
Passed Both5
Signed into Law119th
Congress
2026-10-29
Introduced
2
Cosponsors
HR
ⓘType
Sponsor
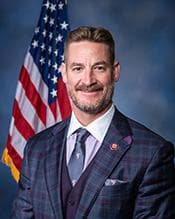
W. Gregory Steube
Republican · FL · Representative
Votes with party: 90.3% (652 recorded votes)
Full profile: /officials/S001214
Source: Congress.gov · FEC
Cosponsors (2)
Members who have signed on to support this bill since introduction. Source: Congress.gov.
Latest Action
The most recent step in the bill's legislative path. Committee Activity below shows referrals and reports; the full action-by-action history including floor proceedings lives at Congress.gov →
Committee Activity
Currently in
- House Committee on Ways and MeansReferred To · 2026-10-29
Plain-English Summary
Plain-English summary pending. Introduced on 2026-10-29. Check back soon — summaries are generated as bills progress through Congress.
Full Bill Text
Verbatim text published on Congress.gov via GovInfo. Use Cmd+F / Ctrl+F to search within this excerpt.
[Congressional Bills 119th Congress] [From the U.S. Government Publishing Office] [H.R. 10944 Introduced in House (IH)] <DOC> 119th CONGRESS 2d Session H. R. 10944 To amend the Internal Revenue Code of 1986 to exclude from gross income certain retirement plan distributions used for a down payment or closing costs for a principal residence, and for other purposes. _______________________________________________________________________ IN THE HOUSE OF REPRESENTATIVES October 29, 2026 Mr. Steube (for himself, Mr. Panetta, and Mr. Carey) introduced the following bill; which was referred to the Committee on Ways and Means _______________________________________________________________________ A BILL To amend the Internal Revenue Code of 1986 to exclude from gross income certain retirement plan distributions used for a down payment or closing costs for a principal residence, and for other purposes. Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled, SECTION 1. SHORT TITLE. This Act may be cited as the ``Homeownership Opportunity Act''. SEC. 2. EXCLUSION FROM GROSS INCOME OF RETIREMENT PLAN DISTRIBUTIONS USED FOR A DOWN PAYMENT OR CLOSING COSTS FOR A PRINCIPAL RESIDENCE. (a) In General.-- (1) Defined contribution plans.--Section 402 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection: ``(m) Distributions for a Down Payment or Closing Costs for a Principal Residence.-- ``(1) In general.--The gross income of an employee for any taxable year shall not include any distribution from a defined contribution plan (as defined in section 414(i)) of such employee to the extent that such distribution is used for a down payment or closing costs associated with acquiring a principal residence (within the meaning of section 121) of the employee. ``(2) Limitation.--The aggregate amount of distributions received by an individual to which paragraph (1) applies for any taxable year shall not exceed an amount equal to the excess (if any) of-- ``(A) the greater of-- ``(i) $40,000, or ``(ii) an amount equal to 40 percent of the employee's vested account balance in the plan as of the date of distribution, over ``(B) the sum of-- ``(i) the aggregate amount of distributions received by such individual to which paragraph (1) applied for all prior taxable years, plus ``(ii) the aggregate amount of distributions received by such individual to which section 403(d)(1) or 457(e)(19)(A) apply for the taxable year, plus any such amounts for all prior taxable years. ``(3) Amount distributed may be repaid.-- ``(A) In general.--Any individual who receives a distribution to which paragraph (1) applies may, at any time during the 3-year period beginning on the day after the date on which such distribution was received, make one or more contributions in an aggregate amount not to exceed the amount of such distribution to an applicable eligible retirement plan of which such individual is a beneficiary and to which a rollover contribution of such distribution could be made under section 402(c), 403(a)(4), 403(b)(8), 408(d)(3), or 457(e)(16), as the case may be, except that such a contribution may only be made to an individual retirement plan if the individual has separated from employment with the employer maintaining the plan from which the distribution was made. ``(B) Limitation on contributions to applicable eligible retirement plans other than IRAs.--The aggregate amount of contributions made by an individual under subparagraph (A) to any applicable eligible retirement plan which is not an individual retirement plan shall not exceed the aggregate amount of distributions which are made from such plan to such individual to which paragraph (1) applied. Subparagraph (A) shall not apply to contributions to any applicable eligible retirement plan which is not an individual retirement…
Show the remaining 684 wordsHide the remaining 684 words
plan unless the individual is eligible to make contributions (other than those described in subparagraph (A)) to such applicable eligible retirement plan. ``(C) Treatment of repayments of distributions from applicable eligible retirement plans other than IRAs.-- If a contribution is made under subparagraph (A) with respect to a distribution from an applicable eligible retirement plan other than an individual retirement plan, then the taxpayer shall, to the extent of the amount of the contribution, be treated as having received such distribution in an eligible rollover distribution (as defined in section 402(c)(4)) and as having transferred the amount to the applicable eligible retirement plan in a direct trustee to trustee transfer within 60 days of the distribution. ``(D) Applicable eligible retirement plan.--The term `applicable eligible retirement plan' means an eligible retirement plan (as defined in subsection (c)(8)(B)) other than a defined benefit plan. ``(4) Application of section 72.--Rules similar to the rules of section 408(d)(10)(C) shall apply for purposes of this subsection, by taking into account all amounts in the defined contribution plan to which the employee has a nonforfeitable right in lieu of all amounts in all individual retirement plans of the individual. ``(5) Distributions treated as meeting plan distribution requirements.--For purposes of this title-- ``(A) a distribution to which paragraph (1) applies shall be treated as meeting the requirements of sections 401(k)(2)(B)(i), 403(b)(7)(A)(i), 403(b)(11), and 457(d)(1)(A), and ``(B) in the case of a money purchase pension plan, a which is an in-service withdrawal shall be treated as meeting the requirements of section 401(a) applicable to distributions. ``(6) Termination.--This subsection shall not apply to any distributions in taxable years beginning after December 31, 2035.''. (2) Certain annuity plans.--Section 403 of such Code is amended by adding at the end the following new subsection: ``(d) Distributions for a Down Payment or Closing Costs for a Principal Residence.-- ``(1) In general.--Rules similar to the rules of section 402(m) shall apply to distributions under an annuity contract subject to subsection (a) or under an annuity contract described in subsection (b). ``(2) Limitation.--The aggregate amount of distributions received by an individual to which paragraph (1) applies for any taxable year shall not exceed an amount equal to the excess (if any) of-- ``(A) the greater of-- ``(i) $40,000, over ``(ii) an amount equal to 40 percent of the employee's vested account balance in the contract as of the date of distribution, over ``(B) the sum of-- ``(i) the aggregate amount of distributions received by such individual to which paragraph (1) applied for all prior taxable years, plus ``(ii) the aggregate amount of distributions received by such individual to which section 402(m)(1) or 457(e)(19)(A) apply for the taxable year, plus any such amounts for all prior taxable years. ``(3) Termination.--This subsection shall not apply to any distributions in taxable years beginning after December 31, 2035.''. (3) 457(b) plans.--Section 457(e) of such Code is amended by adding at the end the following new paragraph: ``(19) Distributions for a down payment or closing costs for a principal residence.-- ``(A) In general.--Rules similar to the rules of section 402(m) shall apply to distributions under an eligible deferred compensation plan established and maintained by an employer described in paragraph (1)(A). ``(B) Limitation.--The aggregate amount of distributions received by an individual to which subparagraph (A) applies for any taxable year shall not exceed an amount equal to the excess (if any) of-- ``(i) the greater of $40,000 or an amount equal to 40 percent of the employee's vested account balance in the plan as of the date of distribution, over ``(ii) the sum of-- ``(I) the aggregate amount of distributions received by such individual to which subparagraph (A) applied for all prior taxable years, plus ``(II) the aggregate amount of distributions received by such individual to which section 402(m)(1) or 403(d)(1) apply for the taxable year, plus any such amounts for all prior taxable years. ``(C) Termination.--This paragraph shall not apply to any distributions in taxable years beginning after December 31, 2035.''. (b) Effective Date.--The amendments made by this section shall apply to distributions made in taxable years beginning after December 31, 2025. <all>
Related legislation
Bills by the same sponsor or covering overlapping subjects.
- HR10606FLAFO ActReferred to Committee · 2026-09-24
- HR10607American Fuel Affordability ActReferred to Committee · 2026-09-24
- HR9498Taxpayer Advocate Participation ActPassed House · 2026-09-16
- HR5366Doug LaMalfa Federal Disaster Tax Relief Certainty ActEnacted into Law · 2026-09-11